
Every strategy and guide published by North Shore is backed by the board-certified expertise of our Co-Founders. With decades of combined experience in holistic admissions, Amy and Debbie ensure our guidance is objective, unbiased, and focused exclusively on your student's best fit.
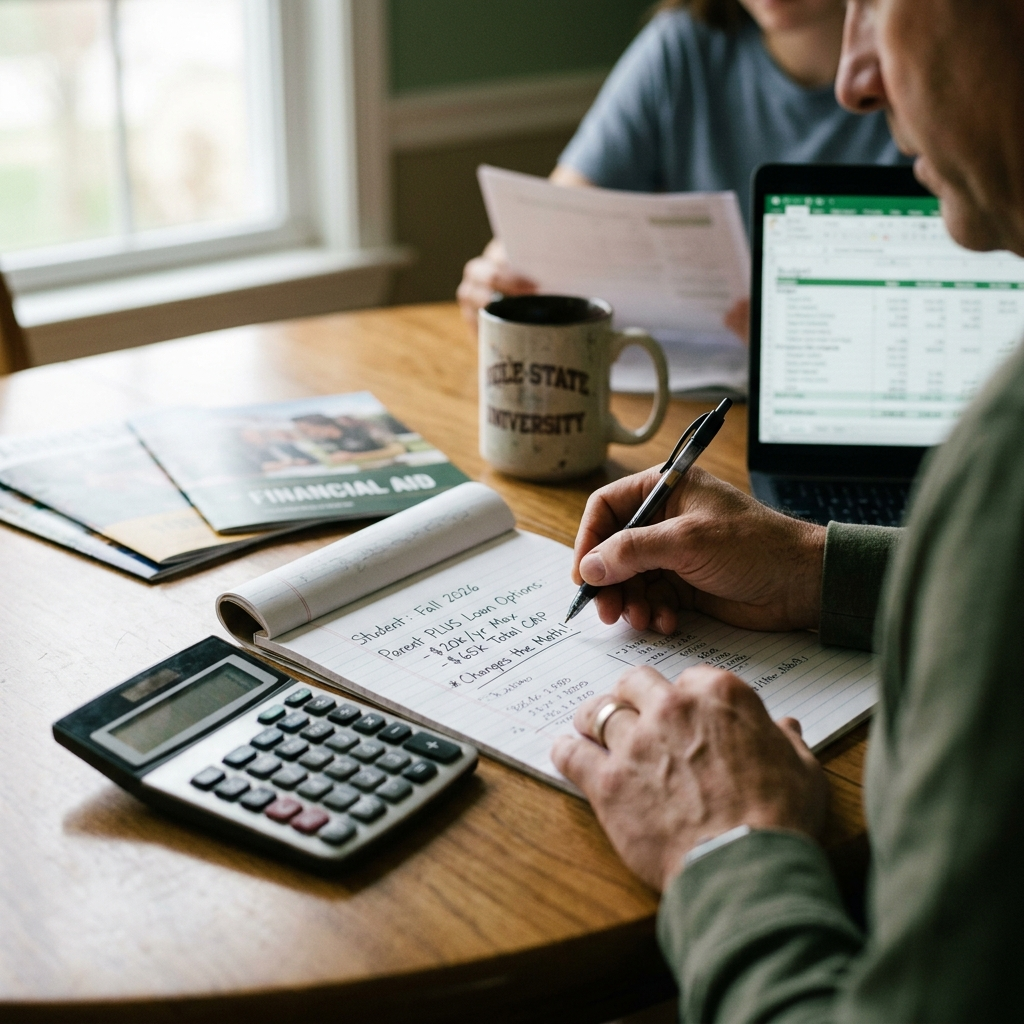
Federal Parent PLUS loans are capped at $20,000 per year and $65,000 in total per dependent undergraduate student for parents whose first PLUS disbursement comes on or after July 1, 2026. The limits are combined across both parents, and amounts repaid or forgiven still count toward the $65,000. Under the old rule, a parent could borrow up to the full cost of attendance minus other aid, every year. For the parent of a current high school senior, no legacy exception applies, because the exceptions require a federal loan disbursed for that student before July 1, 2026.
For two decades, the quiet backstop of college financing was that a parent with acceptable credit could federally borrow whatever the aid package did not cover. Most families never said this out loud. It sat underneath the planning anyway, in the assumption that if the numbers came up short, PLUS would close the gap. That backstop now has a ceiling, the ceiling is well below the four-year cost of most private colleges, and no award letter arriving next spring is obligated to explain that the rule it operates under changed.
The change itself is documented: a statute, an effective date, and a definition of who counts as a new borrower. Those are laid out below and take five minutes to understand. What takes longer, and what this post ends on, is the arithmetic the cap forces across four years rather than one, including the year the money actually runs out and the point on this fall's calendar where a family commits to a price months before any of it can be borrowed.
The July 2025 budget reconciliation law, commonly called the One Big Beautiful Bill Act, capped Parent PLUS borrowing effective July 1, 2026. A parent whose first PLUS disbursement for a student comes on or after that date can borrow up to $20,000 per year for that student, and $65,000 in total across all years.
Three mechanics inside that sentence do the real work. The limits are combined across all borrowers, so two parents borrowing for the same student share one $20,000 annual allowance and one $65,000 lifetime allowance, and divorce does not create a second one. The aggregate is measured without regard to amounts repaid, forgiven, or discharged, so paying a loan down does not restore capacity. And the limits run per student, so borrowing for an older sibling does not shrink a younger child's allowance.
The comparison to the old rule is what makes the number legible. Previously, PLUS had no dollar cap at all. A parent could borrow the full cost of attendance minus other aid, every year, at every college. At a college with a comprehensive cost near $95,000, that was potential borrowing of $380,000 over four years. The same family's federal ceiling is now $65,000. This is not an adjustment. It is a different system.
The student's own federal borrowing did not change and remains modest: for most dependent undergraduates, $5,500 as a freshman rising to $7,500 by junior year, or $27,000 across four years. Put the two together and the federal government will now lend a typical family at most about $92,000 toward a four-year undergraduate degree.
Most of what has been written about this law is aimed at families already in college, so it dwells on the carve-outs. Parents with a federal loan disbursed for a student's current program before July 1, 2026 can generally keep borrowing under the old rules for up to three more academic years or until that student finishes the program, whichever comes first, provided the student stays continuously enrolled in the same program.
Read that definition against a student who is a high school senior right now and the entire exception evaporates. A student entering college in fall 2027 has no program, no enrollment, and no loans disbursed before July 2026, and cannot have them. Every parent of a current senior is a new borrower by definition. The grandfathering that softens this law for current college families does not exist for yours, and the pages built to explain it are answering someone else's question.
One more distinction matters because families conflate the two. A parent denied a PLUS loan for adverse credit triggers additional unsubsidized loan eligibility for the student, a rule that still exists. A parent who reaches the cap triggers nothing. The aid system treats a denial as a hardship and a cap as the plan working as designed [VERIFY: confirm no student eligibility increase at the cap, FSA Handbook or aid office confirmation].
Repayment tightened alongside borrowing. New Parent PLUS borrowing repays through the standard fixed plans, and the consolidation route that once gave PLUS parents access to an income-driven payment is closing for loans consolidated after June 30, 2026 [VERIFY: repayment plan availability for new PLUS borrowers before publish]. The practical translation: a parent considering PLUS at 60 should price the monthly payment on a fixed schedule, not on a hope that a payment plan tied to income will exist later.
Here is the arithmetic no award letter will do for a family.
The annual and aggregate limits do not line up. Four years at $20,000 would be $80,000, but the aggregate stops at $65,000. A family borrowing the annual maximum reaches $60,000 by the end of junior year and enters senior year with $5,000 of federal parent borrowing left. The cap does not bind in the year the family makes the decision. It binds in the year the student is one thesis away from finishing, which is the worst possible year to discover it. Any plan that touches PLUS in year one has to be a four-year plan on paper before the first deposit.
This lands hardest on exactly the family aid offices see most: too much income for meaningful need-based aid, not enough cash flow to write the full check. The gap between a $92,000 federal ceiling and a $350,000 to $400,000 four-year cost is now, by design, a private question. Private loans can fill it for families who qualify, on different terms and without federal protections. Payment plans spread it. Home equity, savings, and the student's earnings carry pieces. Which combination is right is a family financial decision beyond what any admissions consultant or blog post should dictate, and the honest advice is to price the whole gap before choosing the list, not after.
Which is why this rule and the early calendar interact so badly. An Early Decision agreement is signed in the fall, is binding, and commits a family to a price roughly seven months before the first PLUS dollar for that year can be disbursed. Under the old rule, the borrowing capacity behind that signature was effectively unlimited. Under the new one it is $65,000, total, and the release valve for insufficient aid is narrower than families assume, which is its own subject and covered in our post on when Early Decision is a financial mistake. (Blog coming soon!) The net price calculator run before any early application was always good practice. It is now the difference between a commitment a family can keep and one it cannot.
What Your Student Should Do
Three moves, in order.
Run every net price calculator with the cap in the model. The student runs the NPC for each college on the list, then builds the four-year version with the family: total cost, minus projected aid, minus $27,000 of student loans, minus at most $65,000 of PLUS spread across four years. The number left over is the real question each college is asking the family, and it should be known before the list is final.
Have one direct conversation with the aid office at any college where the gap is large. The student emails or calls and asks two questions: how does this college expect families to cover costs beyond the federal loan limits, and what payment plan options exist. The answers vary more than families expect and belong in the list decision, not the April decision.
Re-price any Early Decision plan against the cap before anything is signed. If ED is on the table, the family reruns that college's NPC now and reads the binding language knowing the borrowing behind it is capped. A plan that only works if PLUS covers the gap is a plan written for a rule that no longer exists.
One calendar note worth sitting with. The families most exposed to this change will not feel it this fall, or next spring, or even at the first tuition bill, which the first $20,000 covers. They feel it in year four, when the aggregate runs out, and the students feeling it first are already on campus. For a family starting the process now, the entire cost of that lesson is one afternoon with a spreadsheet in October instead of a crisis in a senior spring.
You don't have to navigate the complexities of college admissions alone. Whether you are aiming for the Ivy League, a top-tier public university, or a highly selective major, our expert counselors are here to help you craft a personal brand that stands out.